Revolut valued at $115bn after employee share sale closes
The secondary sale, priced at about $2,017 a share, was led by five US and British investors and raised no new money for the London-based company, according to…

The secondary sale, priced at about $2,017 a share, was led by five US and British investors and raised no new money for the London-based company, according to people cited in press reports.
Revolut said on Wednesday that it had completed a share sale valuing the company at $115bn, consolidating its position as Europe’s most valuable privately held technology company. The transaction was led by Glade Brook Capital Partners, Coatue, Durable Capital Partners, T. Rowe Price Associates and Baillie Gifford, with both long-standing backers and new global investors taking part.
The deal was a secondary sale, meaning existing shareholders sold stock rather than the company issuing new shares. Revolut did not say how much changed hands. Employees and existing investors were able to sell at around $2,017 a share, and sources said no fresh capital was raised. Revolut ran similar sales for staff in 2024 and 2025, and the price per share was reported by Bloomberg and The Wall Street Journal.
The figure is not a surprise. Tech Funding News reported in July that Revolut was seeking a $115bn price, and the company had confirmed the process was under way. What the closing confirms is that institutional buyers were willing to pay it. Revolut was valued at $75bn in a secondary sale last November, up from $45bn in 2024 and $33bn in 2021. The new valuation is 53 per cent higher than a year ago.
The company points to its accounts to justify the price. Revenue rose 46 per cent in 2025 to $6.0bn (£4.5bn), and pre-tax profit increased 57 per cent to $2.3bn (£1.7bn), lifting the pre-tax margin to 38 per cent. Net profit reached $1.7bn (£1.3bn), up from $1.0bn the year before. At $115bn, investors are paying about 50 times pre-tax profit and roughly 68 times net profit, multiples far closer to those of fast-growing software companies than of listed banks.
The past year has also brought regulatory progress. Revolut fully launched banks in the UK, Mexico, Australia and New Zealand in 2026, obtained banking licences in France, Colombia and Argentina, and received conditional approval for a US national bank charter. The UK licence, granted in March, ended a long period in which Revolut operated as a bank under restrictions after receiving its initial authorisation in July 2024.
The American charter remains incomplete. The Office of the Comptroller of the Currency granted preliminary conditional approval on September 3 for Revolut Bank US. The company still needs to meet the OCC’s conditions, secure deposit insurance from the Federal Deposit Insurance Corporation and approval from the Federal Reserve, and obtain final authorisation before opening. American Banker reported that the regulator made four product lines, including leveraged currency trading, subject to separate supervisory sign-off. Revolut is aiming to launch the US bank next year. Until then it relies on partner banks to serve American customers.
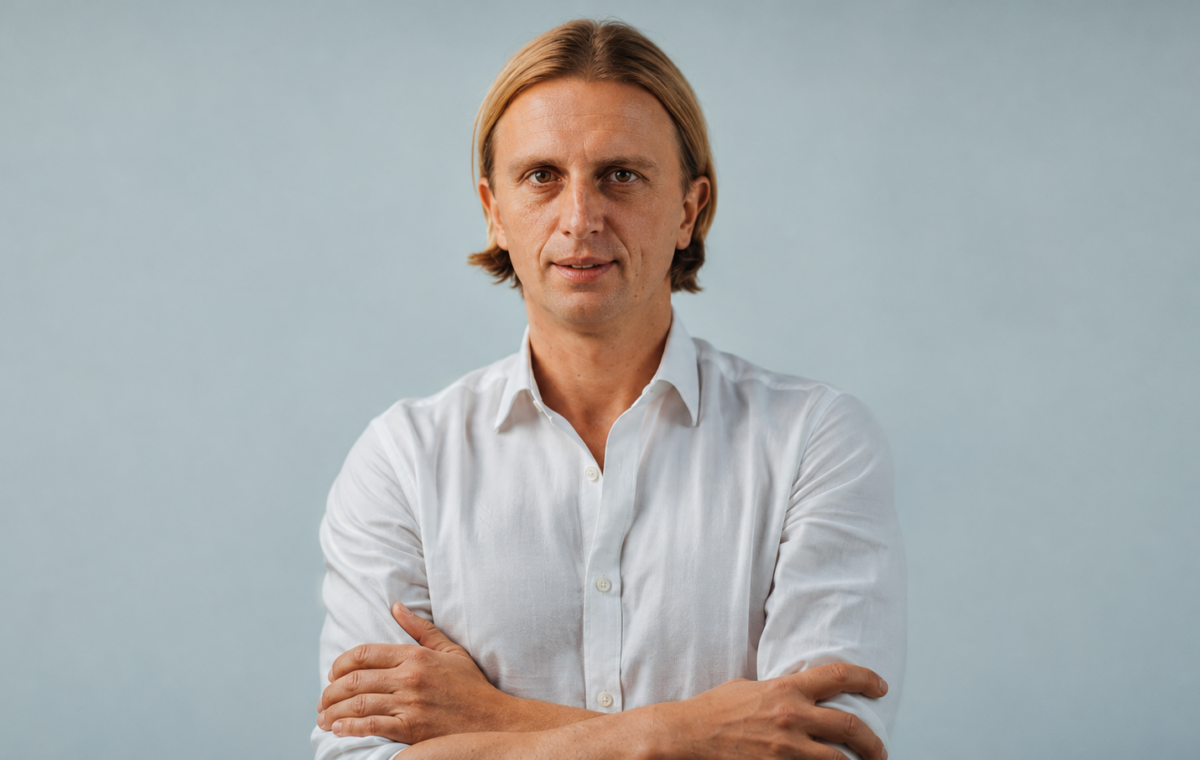
Nik Storonsky, the founder and chief executive, presented the sale mainly as a reward for staff. He said employee ownership had been part of Revolut’s culture from its first day, which was why staff were again offered the chance to sell. In a LinkedIn post, he said the company now had more than 80 million customers and wrote: “100 million next, and a lot more of the world after that.” Revolut has set a target of 100 million customers by mid-2027.
The make-up of that revenue still draws scrutiny. When the $75bn valuation was set last year, analysts noted that much of Revolut’s income came from crypto trading and from interest earned during a period of higher rates. Fee income rose to 76 per cent of revenue in 2025, but the UK and Europe still generated almost all of it, at 25 per cent and 71 per cent of fees respectively.
The secondary sale is widely seen as a step towards a stock market listing. Storonsky said in April that an IPO was at least two years away, putting any offering no earlier than 2028. On October 8 he told Bloomberg TV that Revolut would favour a primary listing in the United States if it went public. He has also said the company is considering a dual listing on the London Stock Exchange and Nasdaq. He has cited deeper liquidity, higher multiples for technology companies and the UK’s 0.5 per cent stamp duty on share dealings as reasons to prefer New York.
Reports have linked the company to a target valuation of $150bn to $200bn at listing. Before then, Revolut needs three more US approvals and a successful American launch, the market that Storonsky has said he wants to dominate.
Written by the newsroom, not a summariser. Free, and you can leave whenever.


0 comments
Anyone can read the thread · subscribers can post