Monzo in talks over possible Nubank sale valuing digital bank at up to £10bn
Monzo, one of Britain’s fastest-growing digital banks, is in early talks over a possible sale to Brazil’s Nubank in a deal that could value the lender at between…

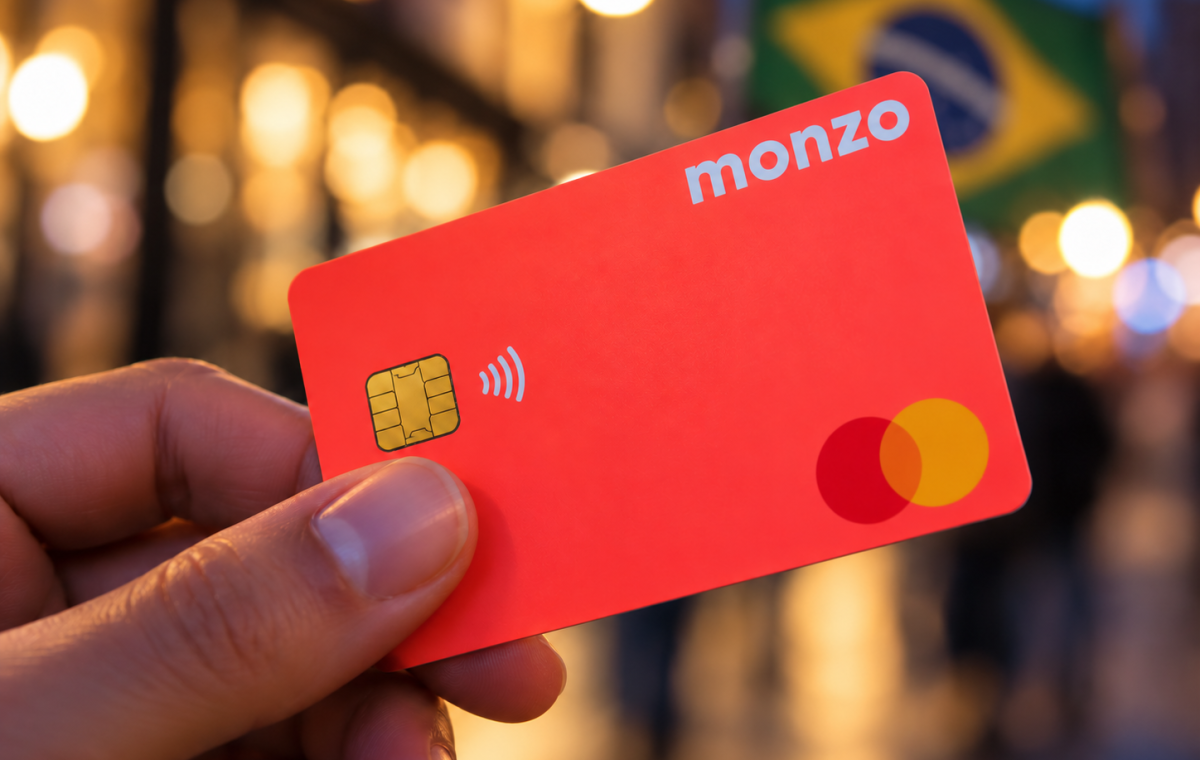
Monzo, one of Britain’s fastest-growing digital banks, is in early talks over a possible sale to Brazil’s Nubank in a deal that could value the lender at between £8 billion and £10 billion.
The discussions, first reported by Sky News, would mark one of the most significant moments yet for the UK fintech sector. Monzo has grown from a challenger banking start-up into a major consumer finance brand, with 16 million customers across its personal and business banking services.
The company has reportedly been approached by Nu Holdings, the New York-listed parent company of Nubank. Nu Holdings has a market capitalisation of $65.5 billion, equivalent to about £49.4 billion, giving it the scale to pursue a multibillion-pound acquisition.
Talks are said to be at a “relatively early stage”, meaning a deal is far from guaranteed. Monzo has brought in advisers from Morgan Stanley and Qatalyst, while outline terms are understood to be under negotiation.
A source close to the process said a sale to Nubank is one of two main options being considered by Monzo’s board and shareholders. The other is a fresh funding round that would value Monzo at more than £8 billion, with proceeds expected to support expansion in mainland Europe.
That choice matters. It suggests Monzo is not simply searching for an exit, but weighing whether it can create more value as an independent company. A funding round at a higher valuation would give the bank fresh capital while allowing existing investors to hold on for future growth. A sale, by contrast, could deliver one of the largest fintech paydays in British start-up history.
Monzo’s customer numbers explain why the bank has become such an attractive target. It now serves around 15 million personal banking customers and 1 million business banking users. In banking, that scale is especially valuable because customers tend to build long-term habits around their primary accounts, payments, savings and lending products.
For Nubank, a deal would offer a powerful foothold in the UK market and a recognisable brand in European digital banking. For Monzo, it would provide the backing of a much larger global fintech group with public-market status and deep experience in app-based financial services.
The financial implications for Monzo’s investors could be substantial. One investor analysis circulating after reports of the talks estimated that a deal worth about $13 billion could generate around $9.3 billion in combined profits for investors on roughly $1.9 billion invested. That would represent a blended return of about 5.8 times across 11 priced funding rounds.
Early backers would stand to gain the most. Passion Capital, which led Monzo’s first three funding rounds and continued investing in later rounds, is estimated to be in line for a particularly large return. The analysis suggested that Monzo’s seed investment alone could return nearly 200 times its money, with Passion’s three seed rounds producing about $1.6 billion of proceeds on roughly $18 million invested.
Goodwater and Thrive are also identified as major winners. Goodwater led Monzo’s Series C round in November 2017 at a $330 million post-money valuation. That round is estimated to be worth more than 20 times invested capital and could generate around $2 billion in proceeds. Thrive, which led the July 2017 Series B round at a $100 million post-money valuation, is estimated to be looking at a return of around 50 times its investment.
Monzo’s crowdfunding investors could also see unusually strong gains. The bank raised three crowdfunding rounds, including its well-known 2016 Crowdcube campaign, which raised £1 million in 96 seconds. Those customers-turned-shareholders are now estimated to be sitting on gains of between 35 and 80 times their investment.
That would make Monzo one of the most successful examples of retail participation in UK technology investing. Crowdfunding campaigns are often risky, and many retail investors in start-ups never see meaningful returns. Monzo’s possible outcome shows the upside when a consumer brand builds both a loyal customer base and a large financial valuation.
The possible sale would also complete a striking turnaround from 2020, when Monzo was forced to raise money at a lower valuation. That down round came at about a $1.7 billion post-money valuation, below its 2019 price. At the time, the outlook was uncertain enough that some questioned whether the company could maintain its momentum.
Investors who backed the bank during that period may now be rewarded for taking the risk. The June 2020 round, involving Novator and Nikesh Arora, is estimated to be on course for a return of about 5.9 times, worth roughly $1.6 billion.
Later-stage investors would still do well, though their gains would be more modest. The Series H round, backed by investors including ADQ, Tencent and Coatue, and the Series I round, involving CapitalG, GV and Hedosophia, are each estimated to return about 2.5 times capital. For large growth-stage rounds, that is a respectable result, though far below the multiples enjoyed by early investors.
Monzo’s founders and employees would also be in line for a significant payout. The investor analysis estimates that founders and the employee share option pool could receive around 15% of the outcome, equal to about $2 billion. That would be a major result for the team, particularly after 11 funding rounds, each of which typically dilutes earlier shareholders.
Still, a deal of this scale would face several hurdles. Banking acquisitions involve regulatory scrutiny, customer protection issues and detailed reviews of capital, compliance and governance. Monzo’s board would also need to decide whether a sale now offers better long-term value than remaining independent and expanding further into Europe.
The wider significance is clear. Britain’s fintech industry has produced several high-profile digital banking names, but few have reached the size where global rivals would consider paying close to £10 billion. A Nubank-Monzo deal would underline how far challenger banks have moved from the fringes of finance into the mainstream.
For customers, there may be little immediate change while talks remain preliminary. But for the fintech sector, the message is already unmistakable: Monzo has become one of the most valuable banking assets in Europe’s digital finance market.
Whether it chooses a sale or another major funding round, Monzo is entering a decisive phase. A company once known for its bright coral cards and start-up energy is now weighing options that could reshape the future of British digital banking.
Written by the newsroom, not a summariser. Free, and you can leave whenever.
0 comments
Anyone can read the thread · subscribers can post